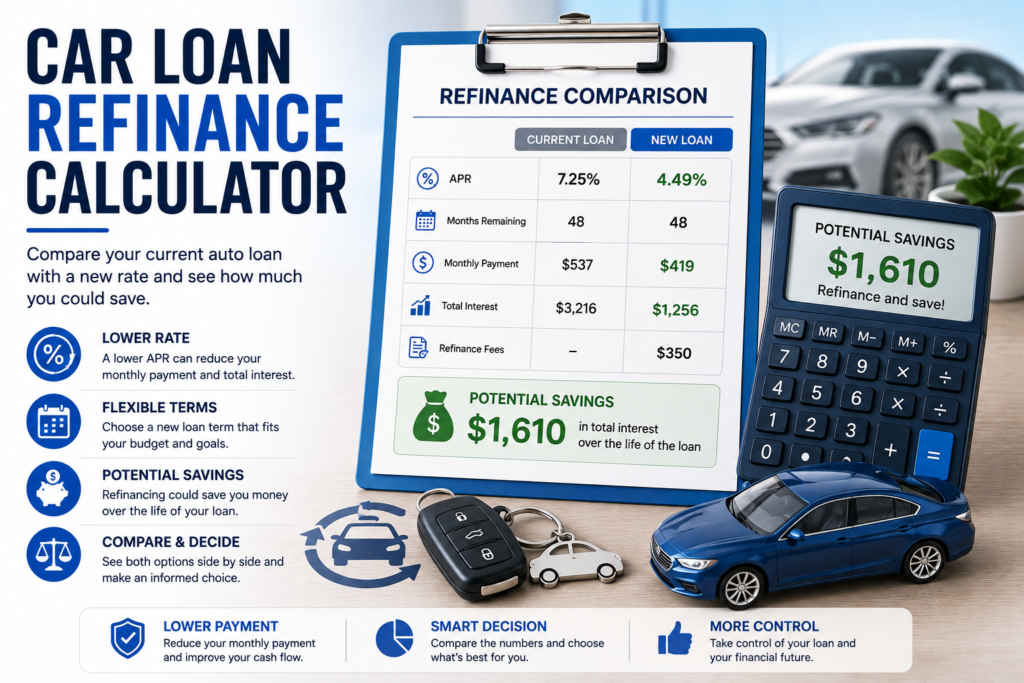
Car Loan Refinance Calculator
Compare your current auto loan with a refinance offer to estimate your new monthly payment, interest savings, total savings, and payoff timeline.
Current Loan
Enter the details of the auto loan you have now.
Refinance Offer
Enter the rate, term and fees for the new loan.
Enter the remaining balance on your current loan, not the original vehicle price. Refinance fees may either be paid upfront or added to the new loan.
Enter your details, then click Compare Loans to see your results.
Current Loan vs Refinance
Compare the estimated cost of keeping your current loan with the refinance offer.
| Loan | APR | Monthly Payment | Term | Interest | Total Future Cost |
|---|---|---|---|---|---|
| Current Loan | 0.00% | $0.00 | 0 months | $0.00 | $0.00 |
| Refinance Loan | 0.00% | $0.00 | 0 months | $0.00 | $0.00 |
How This Car Refinance Calculator Works
This calculator estimates the remaining cost of your current auto loan and compares it with the estimated cost of a new refinance loan.
A lower APR may reduce your monthly payment and interest cost. However, extending the repayment term can sometimes increase the total amount paid even when the monthly payment becomes lower.
For that reason, compare both the monthly payment and total future cost before evaluating a refinance offer.
How to Use the Car Loan Refinance Calculator
Start with the unpaid principal and months remaining on your existing loan, not the original vehicle price or original term. Enter the current annual rate. Then enter the proposed new rate, full new term, and refinance fees. Choose whether those fees are paid now or included in the replacement loan.
Car Loan Refinance Calculator: 48-Month Example
For $25,000 outstanding with 48 months left at 8.5%, the model estimates a $616.21 monthly payment and $4,577.96 in remaining interest. Refinancing the same balance for 48 months at 5.5%, with no fees, gives approximately $581.41 per month and $2,907.77 in interest. The estimated difference is $34.80 per month and $1,670.19 in total future cost. These are illustrative rates, not offers.
Car Loan Refinance Calculator Fees and Break-Even
If the new loan instead has a $300 fee paid upfront, the same-term example's total savings fall to about $1,370.19. A simple cash-flow break-even estimate is $300 ÷ $34.80, or about nine monthly payment reductions. This shortcut does not measure the exact balance difference if you sell or repay early. Compare the outstanding balances and payoff costs at your expected exit date as well.
If the fee is financed, the new balance becomes $25,300. Both the payment and interest change, so do not subtract the fee from the no-fee result and assume that is the financed-fee answer. Enter the fee and select the correct option in the tool.
Keep the Time Horizon Comparable
First compare the new loan over the same 48 months. Then test a longer term separately. A new 72-month term spreads repayment across two extra years; a smaller payment alone does not prove that refinancing costs less. Interest already paid on the old loan is a past cost and is excluded from this forward-looking comparison.
Car Loan Refinance Calculator FAQs
Why is the current payment different from my statement?
The car loan refinance calculator derives it from the entered balance, rate, and remaining term. Deferrals, daily interest, irregular payments, financed fees, or a modified contract can make that reconstruction differ. Use the result as an estimate and compare against the actual required payment and dated payoff quote.
Does this include every closing cost?
Only the fees you enter. Obtain an itemized quote, check existing-loan prepayment conditions, and ask about title or lien-related charges. Do not count the same charge as both an upfront cost and a financed fee.
Is the displayed APR a qualifying offer?
No. The car loan refinance calculator does not check credit, vehicle age, loan-to-value, or lender eligibility. It treats the rate input as an annual interest rate for monthly amortization; a disclosed APR containing mandatory fees may differ from the contractual payment rate.
Use the extra payment calculator to compare paying the current loan down faster. For background, read CFPB guidance on comparing loan costs. Confirm final terms with both lenders before acting.
A Lower Payment Can Hide Most of the Saving
Use the car loan refinance calculator to test the same $25,000 balance at 5.5% over two new terms. With no fees, 48 months gives a payment of approximately $581.41 and $2,907.77 in interest. At 72 months, the payment falls to about $408.45, but total interest rises to approximately $4,408.20.
Compared with the existing 48-month loan at 8.5%, which has $4,577.96 of modeled remaining interest, the 72-month refinance saves only about $169.76 before fees. Adding a $300 fee paid upfront turns that small full-term saving into approximately $130.24 of additional cost. The much smaller installment does not, by itself, show the cost of extending repayment.
Keep a Record of Both Comparisons
Run the car loan refinance calculator first with the new term equal to the old loan’s remaining term. Save that result as the rate-change comparison. Then run the longer proposed term and label it separately as a repayment-extension scenario. Record the fee treatment alongside each result so that upfront cash and financed charges are not confused.
If your current contractual payment differs from the reconstructed payment, ask the servicer for the actual remaining schedule and payoff quote. A prior deferral or extra payment may explain why a monthly model cannot reproduce your statement exactly. Do not change the remaining term just to force the displayed payment to match without understanding the reason.
Read our guide to evaluating an auto refinance before comparing final written offers. Check that the replacement lender’s payoff will satisfy the existing account and confirm the timing with both servicers. This calculator does not arrange the refinance or transmit instructions to either lender.